

Perpay - Shop and Build Credit
by Perpay Inc.
4.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.8
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
I approached Perpay - Shop and Build Credit as a finance app for a very specific starting point: you need household items, but you also want your regular paycheck to support a longer-term credit-building plan. That combination is what makes it different from a normal shopping app or a standard budgeting tool. In my experience, the useful question is not simply “Can I buy this?” but “Will this purchase fit comfortably into the way I already get paid?”
The app is free, available to everyone, and comes from Perpay Inc. It has reached over a million installs, with an average rating of 4.8 from around thirteen thousand ratings. Those figures suggest that the concept is resonating with a sizable audience, but they do not remove the need to examine the practical workflow. Finance products can look simple at the entrance and become complicated once shopping, identity details, payment timing, and credit goals meet in the same process.
From an immediate purchase to a more deliberate paycheck routine
The most realistic use case is someone who needs a necessary item but does not want to rely on a conventional credit card or a large one-time payment. Imagine replacing a basic appliance or buying several useful household products after a move. With a traditional retailer, the process ends at checkout. With Perpay, the purchase is only one part of the experience; the other part is arranging the repayment around income and treating the activity as part of a credit-building routine.
That distinction matters. I would not open this app expecting a general-purpose bank account, a full financial dashboard, or a replacement for every shopping service I use. Its appeal is narrower and more practical: it connects shopping with paycheck-based repayment and credit progress. If that is your situation, the app has a clear purpose. If you only want the lowest possible price, a broad marketplace may be easier to compare.
Before starting, I would prepare the information needed to describe my income and employment situation accurately. I would also decide whether the purchase is genuinely necessary and whether the future deductions would remain manageable during an expensive month. This preparation is one of the less obvious but most important parts of the workflow. The app can organize a payment plan, but it cannot make an unaffordable purchase affordable.
What the first setup is really asking you to decide
The opening experience is less about browsing casually and more about matching your circumstances with the service. I found it helpful to think in terms of a complete cycle: choose an item, understand the repayment commitment, connect that commitment to the way you are paid, and then keep enough room in each paycheck for essentials. Skipping the third step is where many users could get into trouble.
For a person paid on a predictable schedule, this structure can feel more natural than managing a conventional card balance. Instead of waiting for a statement and deciding how much to send later, the user is encouraged to think about the repayment before completing the purchase. That can reduce the temptation to treat available credit as free money. The trade-off is that the commitment becomes part of your regular cash-flow planning, so a change in work hours or an unexpected bill deserves attention immediately.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
I also recommend checking the app’s current terms and the details shown during the actual application or purchase process rather than relying on a general impression. Finance products can vary by user circumstances, and the screen in front of you is more useful than assumptions made from another person’s experience. This is especially important if your income is irregular or your employment situation has recently changed.
Browsing with a purpose instead of shopping on impulse
The shopping side is most useful when I enter with a short list. I might need a particular kitchen item, a replacement device, or something required for a new apartment. Searching with that goal keeps the app from becoming a source of unnecessary spending. I compare the item’s total cost with what I would pay elsewhere, then consider whether the convenience of the repayment structure justifies any difference.
This is a key trade-off compared with buying directly from a retailer. A conventional store may offer more brands, more delivery choices, or a faster comparison of competing prices. Perpay’s value is not automatically that every product is the cheapest. Its value is the way the purchase is tied to a payment routine and a credit objective. I would use it when that structure solves a real problem, not merely because installment-style shopping makes an item feel easier to obtain.
A useful habit is to calculate the purchase in two ways before moving forward. First, look at the complete amount you are committing to. Second, imagine the effect on several ordinary paychecks, including one with an unexpected expense. If the second view feels uncomfortable, I would postpone the purchase or choose a less expensive option. That simple pause is more valuable than any browsing shortcut.
The handoff from shopping to repayment
The central handoff occurs when the item stops being a product in a catalog and becomes a recurring financial obligation. This is where I would slow down and read every amount, schedule, and condition displayed in the app. The attractive part of a smaller paycheck-based payment can hide the fact that the commitment lasts beyond the excitement of receiving the item.
Perpay’s approach is designed around making your paycheck work harder, but that phrase should be interpreted carefully. A paycheck is not extra money; it is money already assigned to rent, food, transport, utilities, and other priorities. The app works best when the planned repayment is placed after those essentials in your budget, not when it is used to stretch an already tight income.
For someone who is paid regularly, the handoff may be straightforward: review the arrangement, follow the required steps, and monitor the deductions or payments as they occur. For someone whose income changes from week to week, the same process requires more discipline. I would keep a separate reminder for each expected payment and review the balance after payday rather than assuming everything will happen exactly as planned.
This is also where the app differs from a basic credit card. A card offers broad spending flexibility, which can be useful but can also encourage multiple purchases to accumulate. Perpay’s more focused shopping-and-repayment model may be easier to understand for users who want one defined purchase at a time. On the other hand, a card or personal finance app may be better for someone who needs a broader overview of all accounts and spending categories.
How credit-building fits into the workflow
The credit-building goal is the reason many people will consider this app, but it should not be treated as an instant transformation. Credit progress depends on responsible behavior and on how the relevant activity is handled over time. I would think of the app as a tool that can support a routine, not as a shortcut that replaces steady payments and careful borrowing.
The most practical strategy is to start with a purchase that is comfortably within your budget. Choosing the maximum amount simply because it appears available defeats the purpose. A smaller commitment that you can maintain is more sensible than a larger one that creates missed-payment risk or forces you to sacrifice necessities. This is one of the strongest non-obvious lessons in using the service: the best credit-building purchase may be the least exciting one.
I would also avoid opening the app only when I want something new. A healthier workflow is to check the status of the existing commitment, confirm that the payment routine is still comfortable, and only then consider another purchase. That turns the service into a controlled financial habit rather than a revolving shopping invitation.
Users should keep their expectations realistic. Credit outcomes are personal, and no app can guarantee a particular result for every person. If your main goal is to understand all your credit accounts, dispute errors, or monitor a complete credit profile, a dedicated credit-monitoring service may be a better companion. Perpay is more focused on the relationship between a purchase, repayment, and credit-building behavior.
Everyday scenario: replacing a needed item without losing control
Consider a worker who needs a replacement appliance after the old one stops working. Paying the entire amount immediately would interfere with groceries and transportation, while using a conventional card would add another balance to an already busy financial life. In that situation, I would browse for the required item, compare the full cost with alternatives, and then examine how the repayment would fit across upcoming paychecks.
The important handoff is not the moment the item is selected. It is the moment the worker decides whether the future payments remain safe after rent and other fixed expenses. If the answer is yes, the app may offer a more structured route than an open-ended card balance. If the answer is no, the correct outcome is to wait, find a cheaper item, or use a different solution. The app should not be used to disguise a gap in income.
After the purchase, I would treat the repayment like any other bill. I would check that the expected payment has been handled, keep the confirmation or transaction record, and avoid adding another commitment until the first one feels routine. That workflow makes the credit-building objective secondary to the more important goal of staying financially stable.
Where the experience can become frustrating
The first possible friction is eligibility and setup. Finance apps need accurate personal and income information, and users may feel that the process takes more effort than ordinary shopping. That is not necessarily a flaw, but it changes the mood of the experience. Someone hoping to buy quickly may find the financial checks and decisions slower than a standard checkout.
The second issue is product choice. A specialized shopping service may not match the range, price, or availability of a large retailer. If you already know the exact model you want, I would compare it outside the app before committing. The convenience of a structured payment plan should be weighed against product selection and total cost, not considered in isolation.
The third issue is cash-flow risk. A payment that looks small on a good payday can feel very different after reduced hours, medical costs, travel, or a family emergency. This is why I would not recommend the app to someone who is already missing bills or has no buffer at all. Adding a new obligation in that situation can make the underlying problem harder to manage.
There is also a psychological friction point: shopping and credit-building are placed close together. That can be helpful for a disciplined user, but it may encourage unnecessary purchases for someone who responds strongly to available payment options. If you tend to buy first and calculate later, a plain budgeting app or a savings plan may be safer.
Who should use it, and who should choose another route
I see Perpay as a good fit for a person who has a regular paycheck, needs a practical purchase, wants a defined repayment structure, and is willing to read the financial details carefully. It may also suit someone who finds a conventional credit card too open-ended and prefers to connect one purchase with one deliberate payment routine.
I would be more cautious recommending it to someone with unstable income, several overdue obligations, or a habit of using new credit to cover old debt. The app cannot replace emergency savings, debt counseling, or a realistic spending plan. It is also not my first choice for someone who wants a complete view of investments, bank accounts, subscriptions, and household categories in one place. A dedicated budgeting or banking tool would serve that broader need better.
Compared with buy-now-pay-later services, the distinctive appeal here is the emphasis on paycheck use and credit-building rather than simply splitting a retail purchase. Compared with a credit card, the structure may be easier to keep tied to a defined purchase, though it may offer less general flexibility. Compared with saving first, the app provides access sooner but introduces an obligation that saving would avoid. None of these options is universally best; the right choice depends on whether your priority is immediate access, flexibility, credit history, or avoiding new debt.
What I would check before committing
I would begin by confirming the exact total cost and the payment schedule shown for my own situation. I would then compare the same item with ordinary retailers, including any delivery or other checkout costs displayed during the purchase. Next, I would map the expected payment against my actual payday dates and leave room for necessities. This three-part check prevents the monthly or per-paycheck figure from becoming the only number I consider.
I would also make sure I understand what action is expected from me after the purchase. Is there a confirmation to review, a payment status to monitor, or an account detail that needs updating if my employment changes? The safest approach is to treat the app as an active financial account, not a one-time shopping screen. Keeping records outside the app can help if you need to reconcile your budget later.
Finally, I would decide in advance what would make me stop using the service. For me, that would include a payment becoming difficult, a change in income, or discovering that the same product is substantially better priced elsewhere. Having that rule before shopping reduces the chance that convenience will override judgment.
My experience with the current app
The current release is version 3.8.3, and the app has been available since October 19, 2018. I appreciate that the product has a clear identity rather than trying to be every type of finance tool at once. The simple idea—shop while organizing repayment around your paycheck and credit goals—gives the experience a practical center.
At the same time, the app’s usefulness depends heavily on the user’s financial habits. The interface can guide a decision, but it cannot decide whether a purchase belongs in your budget. I found the strongest benefit in the planning handoff: turning a vague desire to “build credit” into a specific, manageable purchase and a payment routine. I found the greatest risk in confusing that structure with extra income.
My final recommendation is therefore conditional but positive. If you have stable income, a genuine need, and enough room in your budget, Perpay can be a thoughtful alternative to a conventional credit card or an unstructured installment purchase. Use it slowly, compare prices, and review every commitment before accepting it. If your finances are already under pressure or you need a full banking and budgeting solution, I would choose a different tool and focus on stability first.
Perpay - Shop and Build Credit is best understood as a bridge between shopping and financial routine, not as a promise of effortless credit improvement. Used with restraint, it can make a necessary purchase more deliberate and connect repayment behavior with a longer-term goal. The outcome depends less on how much the app lets you buy than on whether you can complete the entire journey—from paycheck to purchase to final payment—without putting essential spending at risk.
Pros
- Shop now and split eligible purchases into manageable payments.
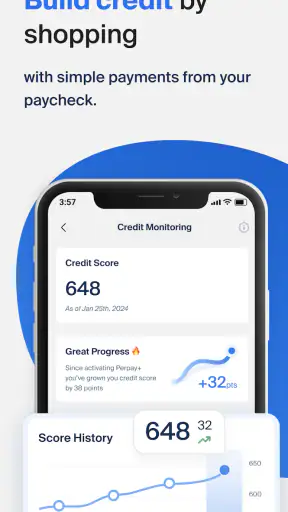
- Reports eligible on-time payments to help build your credit history.
- No hard credit check is required to apply for Perpay.
- Offers access to products without using a traditional credit card.
- Credit-building progress and payment details are easy to track in-app.
Cons
- Product prices may be higher than those at other retailers.
- Missed payments can affect your account and credit-building progress.
- The selection is smaller than on major shopping platforms.
- Spending limits may be low until you establish a payment history.
- Availability and terms can vary depending on your employment and profile.
FAQs for Perpay - Shop and Build Credit
What is Perpay - Shop and Build Credit?
Perpay is a shopping and credit-building platform that lets eligible users purchase products through a pay-over-time plan while potentially reporting qualifying payments to major credit bureaus. After creating an account, you can browse available items, review payment terms, and choose a schedule that fits your income. Availability, approval, limits, and reporting may vary by user and location.
Can Perpay really help me build my credit score?
Perpay may help users establish or improve credit by reporting eligible payment activity to credit bureaus, provided the account and plan qualify. On-time payments are important, while missed or late payments could negatively affect your credit profile depending on the reporting arrangement. Results are not guaranteed, and building credit takes time. Always read the current reporting and account terms before enrolling.
Do I need good credit to use Perpay?
Perpay is designed for people who may have limited, fair, or damaged credit, so a traditional high credit score may not be required for every user. However, approval is not automatic. The service may review information such as identity, income, employment, and payment history when determining eligibility and purchase limits. Requirements can change, so check the in-app application details.
How do Perpay payments work, and are there extra fees?
Perpay generally divides a purchase into scheduled installments that may be collected through a linked payment method or payroll-related arrangement, depending on the plan offered to you. Before confirming an order, review the total cost, installment amount, payment frequency, shipping charges, and any applicable fees. Missing payments can cause account restrictions, additional consequences, or possible credit-reporting issues.
Is Perpay safe to use, and what should I check before downloading it?
Perpay uses account and payment information to process purchases and manage credit-related services, so users should download the official app from Google Play or the Apple App Store and verify the developer name. Use a strong, unique password and carefully review requested permissions. Before buying, inspect the privacy policy, financing disclosures, return rules, customer support options, and cancellation terms.

Perpay - Shop and Build Credit
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via hello@perpay.com, visit https://perpay.com, or review their https://perpay.com/privacy.










